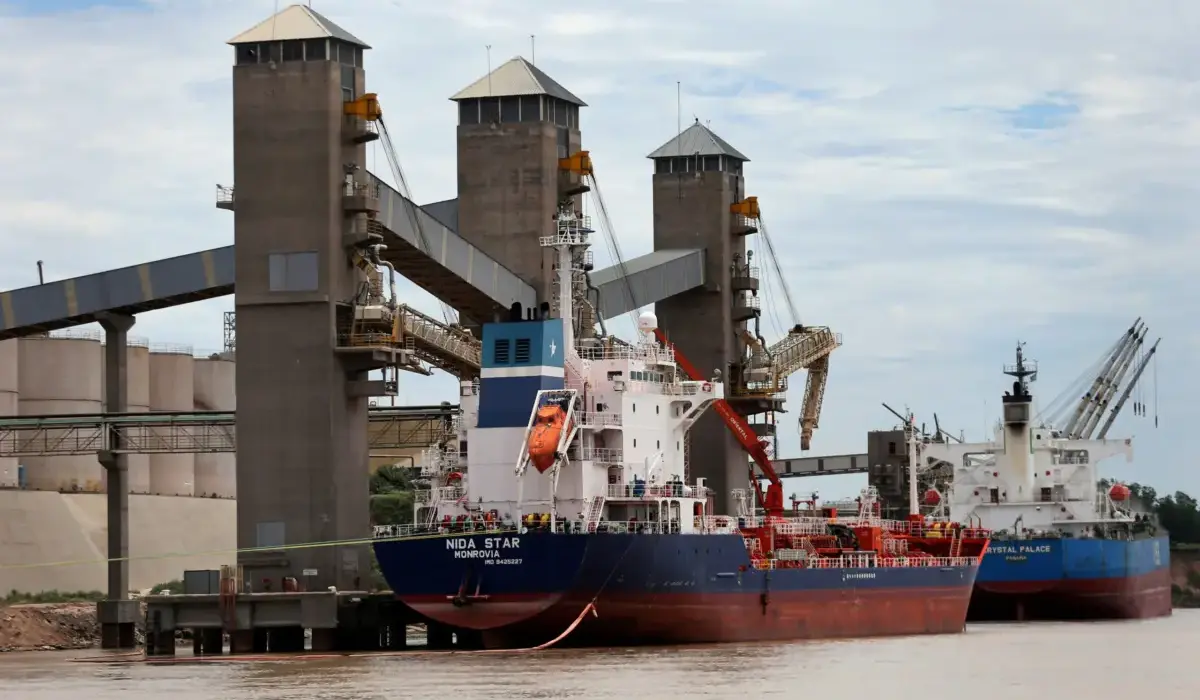
BUENOS AIRES — Propelled by a powerful global surge in oil, mining, and agricultural commodity prices, Argentina is currently experiencing the strongest terms of trade in its entire economic history. This pivotal macroeconomic milestone means that the historical ratio between what the South American nation receives for its exports and what it pays for its imports has climbed to an unprecedented all-time high, filling state coffers and generating significant foreign currency windfalls for primary producers.
However, beneath the surface of these headline-grabbing trade figures lies a stark and increasingly politically sensitive economic paradox. This phenomenal growth within the capital-intensive primary sectors is failing to generate a meaningful spillover effect across the broader domestic economy. Crucial economic pillars—specifically construction, general industry, and domestic commerce—remain severely depressed. According to official data compiled and published by the national statistics institute INDEC, these three vital sectors combined account for fully 37.5 percent of the total workforce in the country.
The growing dichotomy between a record-breaking export performance and a lagging, labor-intensive domestic market is creating a fragile economic climate. Economists and political analysts warn that this unbalanced recovery could weigh heavily on the electoral competitiveness of President Javier Milei’s administration as the country looks ahead to upcoming legislative and presidential contests. While macroeconomic indicators show resilience at the border, the daily reality for millions of Argentine workers navigating a still-weak domestic market tells a fundamentally different story.
Misleading Growth and Statistical Carryover
According to comprehensive macroeconomic projections released by the Buenos Aires-based, center-right think tank Fundación Capital, the Argentine economy is expected to expand by a modest 1.9 percent on a year-on-year basis through 2026.
Yet a deeper analysis of these projections reveals that this anticipated expansion is driven "to a large extent" by the statistical carryover generated from the tail end of 2025, rather than a broad-based, organic economic revival. Furthermore, forecasts indicate that the agriculture, mining, and hydrocarbon sectors alone will account for a full 1.1 percentage points of that projected 1.9 percent growth. Meanwhile, traditional engines of domestic employment and localized economic activity—such as construction, manufacturing industry, and retail commerce—are expected to make little to no positive contribution to the broader national accounts.
The stagnation in these sectors is readily apparent in recent short-term data. During the second quarter of the year, national construction activity registered a contraction of 0.2 percent on a quarter-on-quarter basis, leaving the sector lingering at levels roughly 20 percent below its pre-crisis 2023 baseline.
High-frequency private indicators confirm this deep slump. During the July-August period, the Construya Index—a widely followed private gauge tracking the distribution of private construction materials—alongside domestic cement shipments, plunged by 7.7 percent and 6.4 percent respectively when compared against the figures recorded in the first quarter. Bulk cement shipments, a key bellwether for large-scale infrastructure and private building projects, continued their downward trajectory, marking an average decline of 2.1 percent year-on-year across July and August.
The domestic commerce sector has shown similarly sluggish momentum. Official Gross Domestic Product data published by INDEC revealed a seasonally adjusted 0.8 percent quarter-on-quarter decline in commercial activity during the second quarter. The same official data package confirmed a broader 2.4 percent quarter-on-quarter contraction in private consumption, underscoring the severe constraints facing everyday households.
"Although real incomes bottomed out in the first quarter of the year, the subsequent recovery has been very modest amid continued adjustments to utility rates," Fundación Capital explained in its recent diagnostic report.
Consumer sentiment surveys continue to reflect profound economic fragility. General consumer confidence dipped by another 0.3 percent in the third quarter relative to the previous three-month period, pushing the cumulative decline in confidence to 9.6 percent for the year.
Supermarkets and Industry Point to Persistent Lack of Demand
The underlying weakness of the domestic market was further underscored when INDEC released its latest monthly survey tracking business trends among supermarkets nationwide. According to the corporate respondents, an overwhelming lack of demand remains the single primary factor limiting growth and expansion in the retail sector, cited by 59 percent of surveyed business leaders.
A parallel survey conducted among industrial manufacturing companies yielded remarkably similar conclusions. Over half of the industrial respondents—53 percent—pointed directly to a lack of domestic demand as their principal bottleneck, while an additional 10 percent cited mounting competitive pressures stemming from imported foreign products entering the open market.
Drawing on official state figures, Fundación Capital cautioned that during the first half of the year, only six out of the 24 distinct industrial divisions tracked by statisticians managed to record positive growth. This narrow band of expansion was spearheaded almost entirely by oil refining, which grew by 10.2 percent year-on-year, and the chemicals and chemical products sector, which expanded by 8.1 percent year-on-year.
Conversely, core consumer manufacturing lines remained stagnant or suffered precipitous drops. Food and beverage production remained virtually flat, registering a negligible change of minus 0.1 percent. Meanwhile, the steepest sectoral contractions were concentrated in labor-heavy manufacturing: textiles plunged by 25.3 percent, machinery and equipment manufacturing dropped by 18.9 percent, and the vital motor vehicles and auto parts sector contracted by 11.1 percent.
"Entering the final quarter of the year, economic activity continues to show no broad-based dynamism," the think tank noted in its assessment, warning that "there are no robust growth engines in sight" outside of the heavily export-oriented primary industries.
Looking ahead to the upcoming political and electoral calendar, the think tank cautioned that managing the uneven pace of economic activity "is shaping up to be one of the main challenges" for the government. Projections suggest that economic performance in the upcoming year will likely mirror the uneven patterns observed throughout 2026.
Sectors currently leading the national expansion through global commodity exports are expected to maintain their momentum, while analysts view a pronounced, broad-based recovery in domestic consumption and internal investment sectors as increasingly difficult to anticipate in the near term.