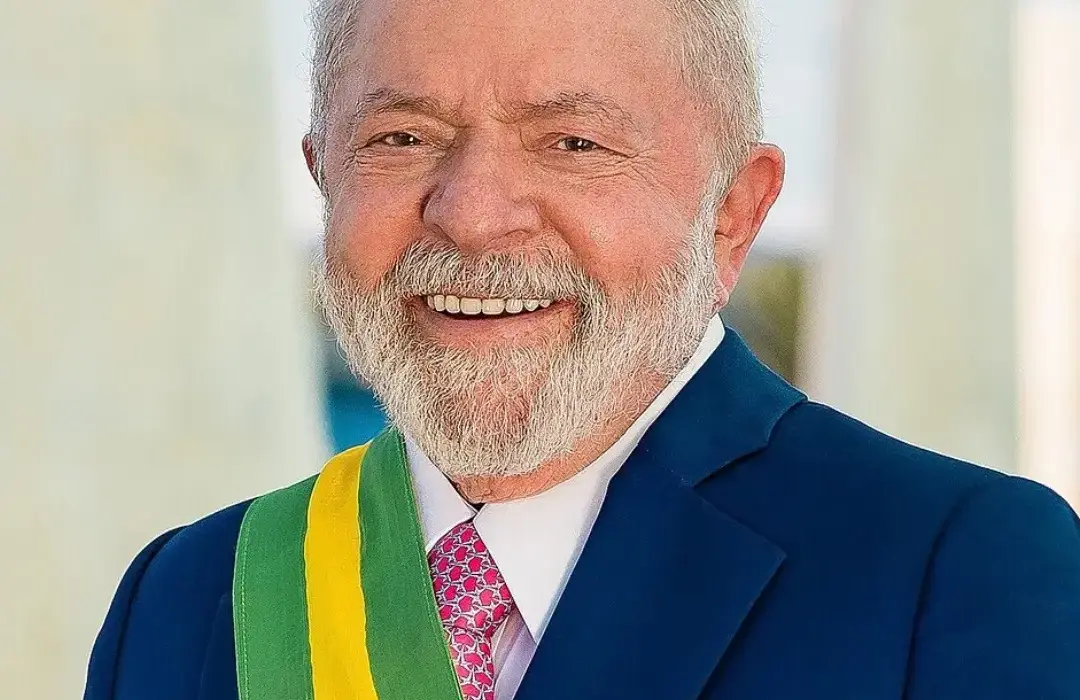
Brazilian President Luiz Inácio Lula da Silva has secured a historic fourth nonconsecutive term in office, defeating conservative Senator Flávio Bolsonaro with 51.79 percent of the vote in a high-stakes electoral showdown. The outcome, finalized on Sunday, October 25, caught many market watchers by surprise, immediately sending shockwaves through financial institutions and thrusting the economic trajectory of Latin America’s largest economy back into the global spotlight.
The political shift was swiftly felt on trading floors. On Monday, Brazil’s benchmark Ibovespa index plunged more than 15 percent during a tumultuous trading session, while the Brazilian real suffered a steep decline, falling more than 11 percent against the US dollar at its weakest point. This dramatic selloff laid bare mounting investor anxieties regarding the nation’s fiscal health and trajectory, particularly as many market participants had increasingly priced in expectations of a Bolsonaro victory.
Beyond the immediate financial turbulence and frantic portfolio adjustments, Lula’s return to power raises fundamental questions for international corporations, particularly American businesses operating in the region. Corporate leaders and trade strategists are now forced to reevaluate what another four years of a Lula administration means for cross-border trade, foreign direct investment, and long-term economic growth opportunities within the Brazilian market.
A $135 Billion Economic Relationship
Despite periodic political divergences and shifts in rhetoric, Brazil remains one of the United States’ most indispensable commercial partners in the Western Hemisphere. Bilateral trade in goods and services between the two economic powerhouses reached an estimated $135.7 billion, according to data from the Office of the United States Trade Representative (USTR).
This robust commercial relationship is especially vital for American exporters looking for high-growth markets outside of North America. Last year, the United States registered a favorable $14.4 billion goods trade surplus with Brazil. American businesses exported $54.3 billion in merchandise to the South American nation while importing $39.9 billion, highlighting a healthy exchange of physical goods alongside diverse service sector engagements.
These figures underscore the reality that economic and commercial relations between Washington and Brasília operate on a plane largely independent of temporary political friction. Brazil continues to serve as a massive destination market for American manufactured products, cutting-edge technology, agricultural inputs, and professional services. At the same time, United States enterprises remain foundational participants in key sectors of the Brazilian domestic economy, ranging from energy and infrastructure to finance and consumer goods.
Even so, the bilateral economic corridor has grown increasingly complicated and fraught with regulatory friction in recent years.
In July, the Trump administration announced an additional 25 percent tariff on the vast majority of Brazilian imports, though targeted exemptions were carved out for specific strategic products. The punitive measures followed a comprehensive Section 301 investigation launched by Washington into Brazilian trade practices, digital commerce regulations, intellectual property protections, electronic payment systems, and barriers to market access. The Brazilian government has consistently disputed the legal and economic justifications behind the U.S. approach, maintaining that its domestic policies comply with international norms.
With Lula securing another mandate, these complex and unresolved trade disputes will remain firmly planted on the bilateral diplomatic agenda. For multinational companies managing supply chains, manufacturing operations, or digital services across both markets, the persistence of these tariffs and regulatory disagreements introduces a persistent layer of operational risk.
The Investment Question
For institutional investors and private equity firms eyeing the region, Brazil’s domestic macroeconomic outlook presents a distinct and multifaceted set of challenges.
The International Monetary Fund (IMF) has projected that Brazil’s economy will expand at a moderate rate of 2.4 percent, following a comparable growth rate of 2.3 percent in the previous year. While this steady, albeit modest, growth demonstrates a degree of underlying resilience in the face of global headwinds, the country continues to grapple with severe and mounting structural fiscal pressures.
According to IMF projections, Brazil’s gross government debt is on track to approach approximately 98 percent of its gross domestic product. This towering debt burden has amplified longstanding concerns among economists and investors regarding runaway public spending, escalating domestic borrowing costs, and the ultimate long-term sustainability of the nation’s public finances.
Financial markets will now be watching closely to see how Lula navigates the delicate political balancing act ahead of him. He must reconcile his administration’s traditional commitments to robust social spending and poverty alleviation programs with mounting demands from domestic and international financial sectors for greater fiscal discipline and structural reform.
The initial composition of his incoming economic team, and most importantly the appointment of his finance minister, will serve as an immediate bellwether for the administration’s true policy priorities. A pragmatic, fiscally conservative appointment could help calm jittery markets, whereas a more interventionist choice might trigger further capital flight and currency depreciation.
For American and international corporations considering capital expansion projects in Brazil, these executive decisions carry immense weight. Macroeconomic variables such as fluctuating interest rates, currency volatility, shifting tax burdens, and regulatory predictability directly influence capital expenditure costs and expected returns on investment. While political continuity under Lula may offer a certain degree of predictability regarding governance style, it does little to alleviate the deep-seated economic uncertainties facing the country.
What Comes Next
Lula’s fourth term in office will officially commence under a complex web of economic and political constraints. He will govern alongside a conservative-leaning National Congress that is fully capable of blocking ambitious legislative agendas, all while facing intense, unsparing scrutiny from global financial institutions regarding Brazil’s fiscal direction.
His immediate priority upon taking office will be to reassure skittish investors and stabilize domestic markets without alienating the working-class base and political allies that secured his narrow electoral victory.
For corporate executives and strategic planners, three key developments will dictate the health of the commercial landscape in the near term: the explicit direction and execution of Brazil’s fiscal policy, the trajectory of ongoing bilateral trade negotiations with Washington, and the evolution of the regulatory environment governing foreign direct investment.
The sharp, volatile market reaction to Lula’s victory serves as a stark reminder of the acute sensitivity surrounding these pending policy decisions. Yet, the sheer depth and historical resilience of the United States-Brazil commercial relationship suggest that economic cooperation will endure, surviving political differences and shifting geopolitical tides.
Ultimately, the long-term implications for American businesses operating within this vital Latin American market will depend far less on the dramatic headlines of election night than on the pragmatic economic policies that follow in the months ahead.