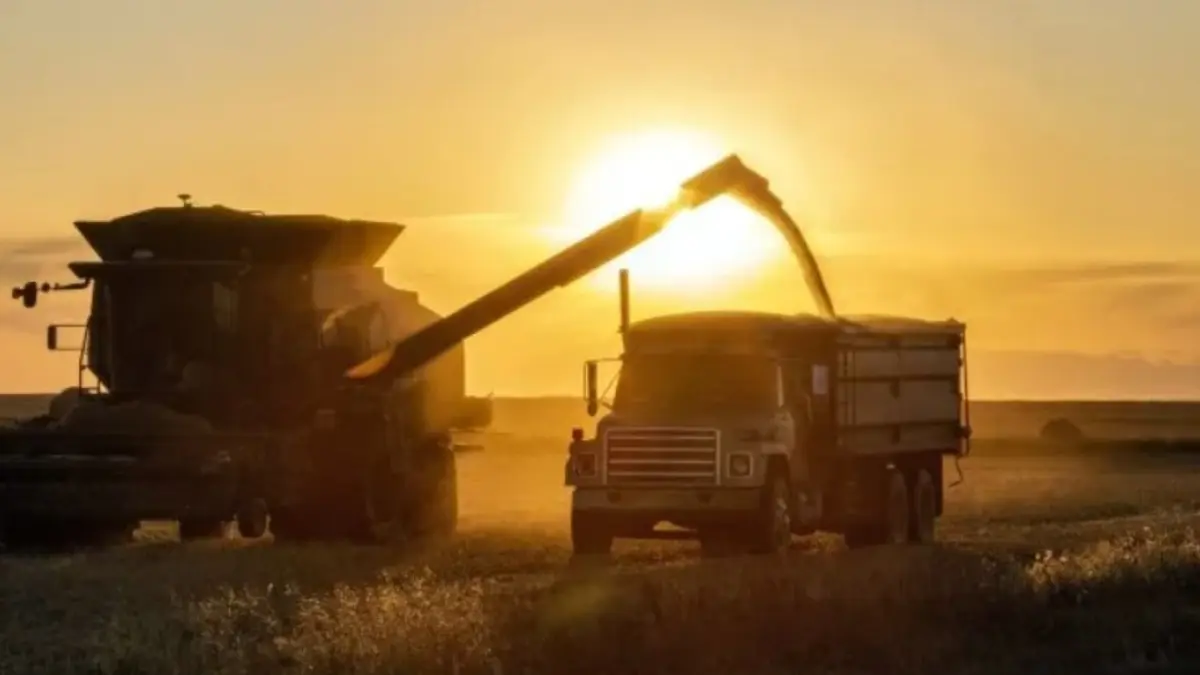
According to comprehensive new estimates released by the Buenos Aires Grain Exchange—widely regarded as one of the most authoritative trade associations and analytical bodies within the South American nation’s agricultural sector—total grain production for the upcoming cycle is projected to reach an unprecedented 158 million tonnes. This ambitious forecast represents a steady 0.5% increase compared to the already robust 157 million tonnes anticipated for the 2026 agricultural cycle.
Building upon these volume projections, the Buenos Aires Grain Exchange anticipates that total economic activity tied directly to the broader agro-industrial sector will surge to approximately US$54 billion. This financial milestone marks a nearly 6% increase compared to the previous operational cycle. Furthermore, agricultural exports are slated to climb to US$41 billion, delivering a healthy 6.9% increase in foreign sales that will directly benefit Argentina’s central bank reserves.
Despite the optimistic outlook, Ramiro Costa, the general manager of the agricultural chamber, has urged caution, clarifying that these macroeconomic projections are not yet set in stone. Speaking to industry stakeholders, the economist emphasized that the figures represent current agricultural potential rather than guaranteed outcomes. He noted that final tallies will ultimately depend on unpredictable meteorological patterns, rainfall distributions, and strategic production decisions made by individual farmers and agribusiness enterprises over the coming months.
Even with the rapid expansion of Argentina’s burgeoning mining sector and the traditional strength of its oil and gas industries in Patagonia, the agricultural sector remains the undeniable powerhouse and primary source of hard foreign currency for the Argentine economy. Trade data illustrates this enduring dominance: between January and August 2026, primary agricultural products and agro-based manufactured goods—excluding meat and meat derivatives—accounted for just over 50% of the total US$67 billion in goods exported by the country. For Buenos Aires, a thriving harvest translates directly into macroeconomic stability.
Looking towards 2027
Among the primary catalysts driving optimism for the upcoming crop year, agricultural leaders have pointed directly to the strategic reduction in export duties implemented by President Milei’s administration earlier this year. The tax adjustments represent a crucial policy shift designed to alleviate the heavy fiscal burden long shouldered by domestic producers.
President Milei officially announced the tariff reductions last May during a high-profile ceremony commemorating the 172nd anniversary of the Buenos Aires Grain Exchange. During his keynote address, the libertarian leader confirmed immediate tax cuts for wheat and barley, lowering export duties from 7.5% to 5.5% effective June 2026. Furthermore, he committed his administration to a gradual reduction in soybean export duties, scheduled to begin in January 2027 and continue progressively through 2028, contingent upon national revenue trends and fiscal balance targets.
During the same organizational presentation, Ricardo Marra, president of the Grain Exchange, emphasized that moving progressively toward the complete elimination of export duties is an absolute necessity. Marra argued that lowering taxes not only improves the profit margins of individual producers but also establishes vital incentives required to stimulate production, encourage long-term capital investment, accelerate technology adoption, and maximize export capacity across the board.
Challenges to overcome
Despite the broadly positive sentiment surrounding government policy shifts and production forecasts, Marra did not shy away from addressing systemic obstacles. He cautioned that true agricultural growth and sector-wide expansion require a level of national competitiveness that extends far beyond the farm gate.
Marra outlined a comprehensive series of structural challenges that Argentina must urgently overcome to sustain higher production and export volumes over the coming decade. Chief among these priorities are critical infrastructure improvements, specifically the modernization and expansion of regional roads, freight railway networks, highway access points to major ports, and the maintenance of deep-water navigation channels. Without these logistics upgrades, higher crop volumes risk running into severe domestic bottlenecks.
In addition to domestic logistics, Marra stressed the pressing need to aggressively expand international market access and deepen the global integration of Argentina’s agribusiness sector. This involves proactively removing foreign trade barriers, successfully forging new bilateral and multilateral trade agreements, and ensuring that Argentina can compete fiercely across an expanding array of global markets with products featuring higher value-added rather than just raw commodities.
Marra’s strategic warnings carry profound economic implications, particularly when viewed through the lens of regional geopolitics and international trade rivalry. Argentina’s most formidable competitor in the global agricultural export market is located right next door within the same trade bloc: its Mercosur partner, Brazil.
The outlook for Mercosur
The fierce agricultural competition and complementary dynamics between Argentina and Brazil took center stage during the presentation of the chamber’s third edition of the Mercosur Outlook. This comprehensive regional forecast models agricultural trends, production capabilities, and export capacities across the trade bloc through the year 2036.
According to data compiled by the chamber, the Mercosur trade bloc—which unites Brazil, Argentina, Uruguay, and Paraguay—currently exports an astonishing US$197 billion worth of food annually to global markets. Within this powerful bloc, Brazil stands undisputed as the world’s leading agricultural exporter, while Argentina firmly holds the position of the world’s third-largest agricultural powerhouse. Combined, these nations command immense leverage in global food security, accounting for 59% of worldwide soybean exports and 36% of global corn exports.
Looking ahead over the next decade, regional projections for the Mercosur agricultural sector point to substantial expansion. Combined cereal and oilseed production across the member states is expected to surge from nearly 535 million tonnes to 591 million tonnes, representing a robust 18.7% growth rate. To accommodate this boom, the total planted area across the bloc is projected to expand by 9.6%, while total export volumes are expected to increase by 18.1%.
A closer examination of the regional growth breakdown reveals distinct specialties among the member nations. Corn is projected to lead the expansion in total physical volume, generating an additional 52 million tonnes of production. Brazil is positioned to capture 64% of this specific corn expansion. Soybeans will follow closely behind, yielding an additional 34 million metric tons, with Brazil accounting for 75% of that soybean growth. Meanwhile, Argentina is set to anchor the region’s wheat production, supplying 74% of an anticipated 5.3-million-tonne increase in regional wheat output, reinforcing the country’s historic role as a premier global supplier of high-quality milling wheat.