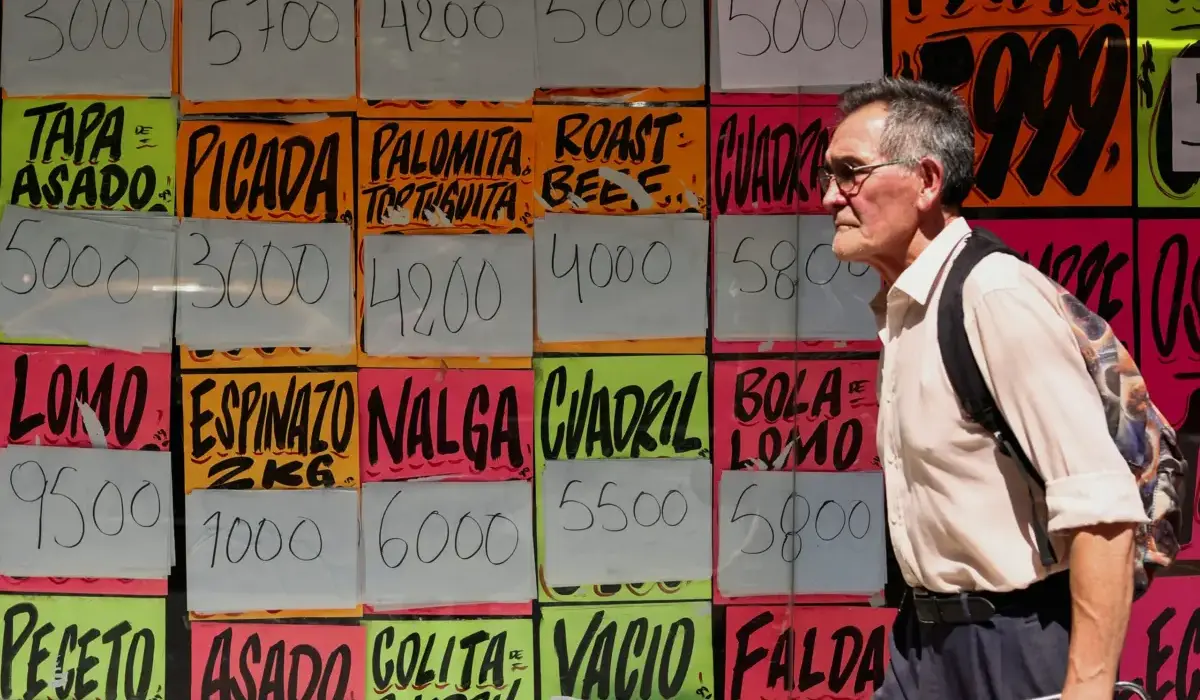
BUENOS AIRES — Inflation in Argentina edged upward in September to reach 1.9%, according to data released on Tuesday by the National Institute of Statistics and Censuses (INDEC).
The latest Consumer Price Index (CPI) report marks a modest acceleration following the 1.7% inflation rate recorded in August, which had previously represented a 13-month low. Despite the slight monthly uptick, economic analysts and market participants have largely received the data with optimism. This perspective is driven largely by the fact that monthly inflation has successfully remained below the psychological two percent threshold for two consecutive months for the first time since the summer period of July and August 2025.
Beneath the headline inflation figure, financial analysts highlighted an even more encouraging indicator: core inflation actually declined. According to the INDEC report, core inflation—which strips out volatile items like seasonal goods and regulated utility tariffs—stood at 1.7% in September, down from 1.8% the previous month. This represents the lowest core inflation reading recorded since July 2025, suggesting that the underlying momentum of price increases across the broader economy continues to cool rather than heat up.
Looking at the broader statistical picture, prices across Argentina rose by 33.4% on a year-on-year basis, while cumulative inflation totaled 23.6% during the first nine months of 2026.
The report also detailed notable regional variations in price pressures across the South American nation. The Greater Buenos Aires area and the economically vital Pampas region both recorded monthly CPI increases of 2%, placing them slightly above the national average. By contrast, price pressures were more contained in other parts of the country. The Northwest and Cuyo regions both posted monthly increases of 1.9%, while the Northeast registered a more moderate 1.7%. The Patagonia region recorded the lowest regional inflation rate in the country for the month, coming in at just 1.4%.
A breakdown of the data by product and service categories revealed that seasonal prices experienced the sharpest upward movement, rising by 2.9%. This seasonal surge was driven primarily by increases in the costs of fresh vegetables, tubers, and legumes. Meanwhile, regulated prices increased by 2.3%, a category heavily influenced by adjustments to household utility bills such as piped gas and electricity, as well as rising costs for private healthcare plans and prepaid medical services.
When examining household expenditures by sector, the largest monthly increases were concentrated in basic utilities and housing maintenance. The division covering housing, water, electricity, gas, and other fuels posted the highest monthly jump at 3.1%, closely followed by the education sector, which saw prices rise by 3%. Conversely, the most modest price adjustments were found in discretionary and lifestyle categories. Restaurants and hotels recorded a minimal increase of just 1.1%, while clothing and footwear prices crept up by 1.4%.
Market Sees Positive Signs
Financial markets and economic analysts quickly weighed in on the INDEC release, with many pointing to the underlying data as evidence of stabilizing economic conditions.
Sergio González, head of the Investment Office at brokerage firm Cohen Aliados Financieros, pointed to the monthly decline in core inflation as the primary "positive data point" within the September report.
"The acceleration came from volatile components and utility tariffs, not from the underlying price trend," González explained, emphasizing that the headline increase was largely driven by factors outside the core economy rather than systemic inflationary pressures. He also noted that the overall inflation figure came in closely aligned with what market participants had anticipated ahead of the release, meaning the data should not trigger any adverse surprises for investors or bondholders.
Federico Filippini, head of research at brokerage firm Adcap Grupo Financiero, expressed a similarly constructive view on the September metrics. Although monthly inflation experienced a slight acceleration compared to August, Filippini stated that "September’s figure offers a fairly positive reading."
Filippini highlighted two main reasons for optimism. First, the official INDEC figure came in comfortably below the higher inflation forecasts that had been circulated by several private consulting firms ahead of the publication. Second, he reiterated that the drop in core inflation to 1.7% "reinforces the signal of an underlying slowdown" in the broader economy.
Furthermore, Filippini noted that the final result came as a relief to many financial actors, pointing out that just a few weeks prior, certain pessimistic sectors of the market had harbored fears of significantly worse macroeconomic results for the end of the third quarter.
Outlook for the Final Quarter
With the third quarter now closed, economists and financial institutions are turning their attention toward the final stretch of the year.
Looking ahead to the coming months, González indicated that the market consensus expects monthly inflation to hover steadily around 1.8%. He noted that this projection implies a slight stabilization and continuation of the broader downward trend following September’s minor reading.
These private market expectations closely mirror the latest Market Expectations Survey (REM), a comprehensive macroeconomic forecast compiled regularly by the Central Bank of the Argentine Republic (BCRA). According to the central bank’s survey, the median private-sector forecast had accurately anticipated September’s 1.9% inflation rate.
Looking forward into the final quarter of the year, the REM survey projects that the average monthly inflation rate will ease down to 1.7% in October. This is expected to be followed by a further marginal decline to 1.6% in November, before experiencing a slight seasonal rebound to 1.8% in December as consumer demand typically picks up during the holiday period.
Based on these monthly trajectories, cumulative annual inflation for the entirety of 2026 is projected by domestic market participants to reach approximately 30%.
At the same time, international financial institutions are monitoring Argentina’s monetary stabilization path closely. In its most recent update on the global and regional economy, the International Monetary Fund (IMF) projected that inflation in Argentina would conclude the year at 32.5%. This revised multilateral projection marks a slight upward adjustment compared to the IMF’s earlier estimate of 30.4% issued back in April, reflecting the gradual pace of price adjustments as the country continues its economic adjustment program.